Dashcam Evidence: How Video Footage Can Prove Fault
A non-fault accident car hire UK service gives you a replacement car
Home » Automotive Blog » At-Fault vs Non-Fault Claims: How Do Claims Work in the UK?
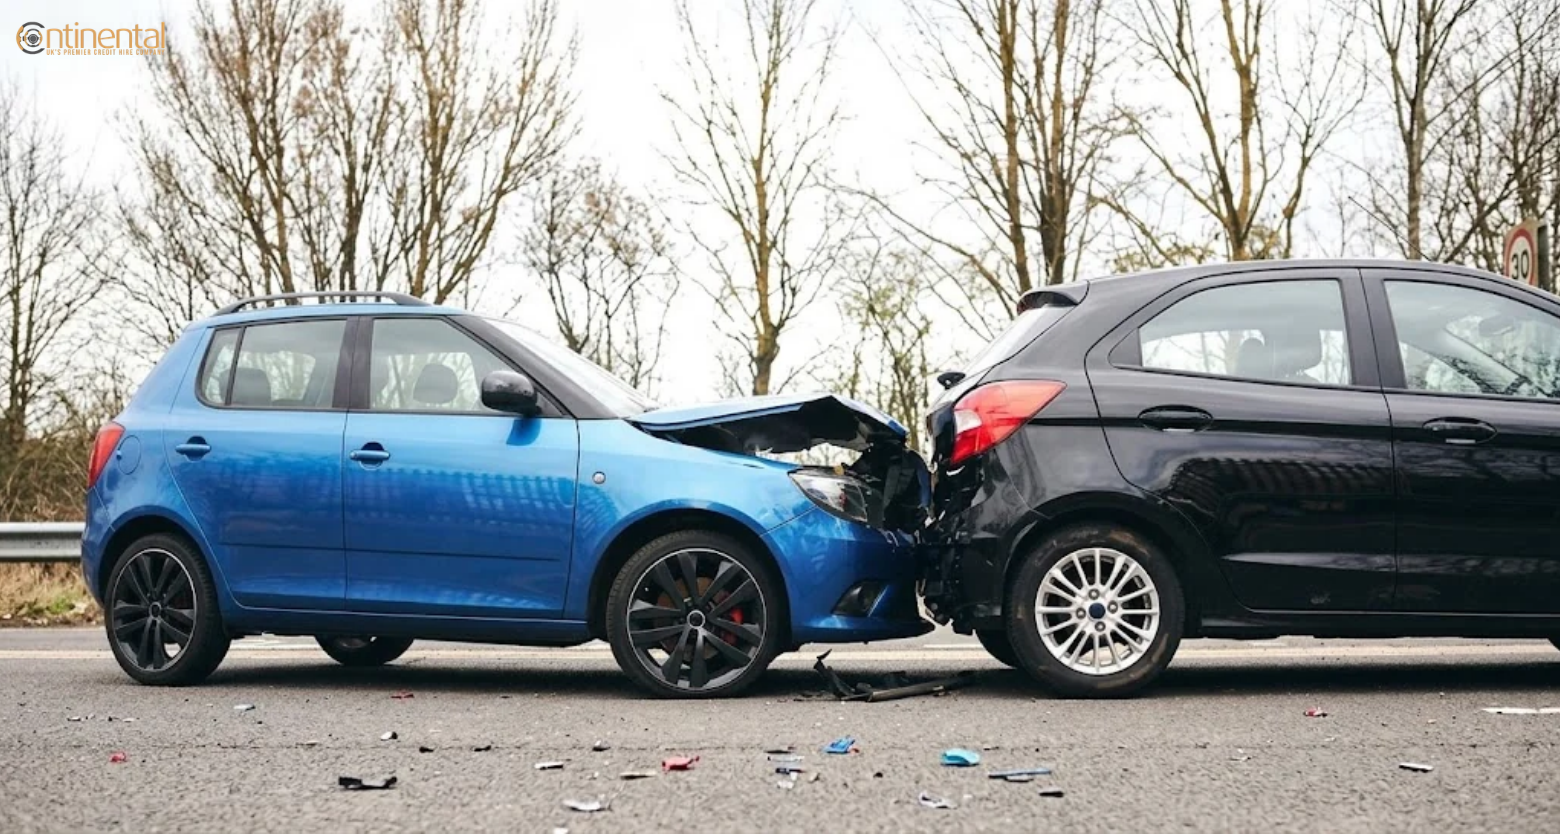
After a car accident in the UK, one question shapes everything that follows: who caused it? If you were at fault, your own insurer pays, and your no-claims bonus usually drops. If you were not at fault, the other driver’s insurer should pay for your repairs, a replacement car, and your other losses.
This guide explains how each type of claim works. You will learn how insurers decide who is to blame, who pays for repairs, what happens when someone has no insurance, and who can get a replacement car.
Key facts
Important: This guide gives general information for drivers in England and Wales. Some rules differ in Scotland and Northern Ireland. It is not legal or financial advice.
An at-fault accident is a crash that you caused, or mostly caused. Common examples include driving into the back of another car, pulling out of a junction into traffic, or reversing into a parked vehicle. Being at fault does not mean you meant to cause harm. It means insurers see you as legally responsible for the damage.
When you are at fault:
What your insurer pays for depends on your level of cover:
Level of cover | Other driver’s losses | Damage to your own car |
Comprehensive | Yes | Yes, minus your excess |
Third party, fire and theft | Yes | No (only fire and theft) |
Third party only | Yes | No |
An at fault accident without insurance is far more serious. In the UK, you must have at least third-party cover to drive on public roads. If you have a car accident without insurance and you are at fault, you break the law, and you may have to pay for all the damage yourself.
The penalties for driving without insurance include:
In a no insurance car accident at fault, the innocent driver can usually still get paid through the Motor Insurers’ Bureau (MIB). The MIB can then try to recover that money from the uninsured driver. That bill can run into thousands of pounds.
A not at fault accident is one that someone else caused. You did nothing to cause or add to the crash. In a car accident where the other driver is at fault, their insurer should pay for your losses.
Common examples of non-fault accidents:
If you were not at fault, you may be able to claim for:
You can claim through your own insurer. They pay for your repairs and then recover the cost from the other driver’s insurer. You may need to pay your excess at first, but you should get it back once your insurer recovers the costs.
You can also claim directly against the at-fault driver’s insurer, often with help from an accident management company. This route keeps the claim off your own policy, so you usually pay no excess.
Example: Priya’s car was parked outside her home in Birmingham when a delivery van reversed into it. The van driver admitted fault and gave his insurance details. The van’s insurer paid for her repairs and a replacement car, and her no-claims bonus stayed the same. This example is for illustration only.
The biggest difference is who pays. In an at-fault claim, your own insurer pays. In a non-fault claim, the other driver’s insurer pays.
At-fault claim | Non-fault claim | |
Who caused the crash | You | Another driver |
Who pays for your repairs | Your insurer (comprehensive cover only) | The other driver’s insurer |
Who pays the other driver’s losses | Your insurer | Their own insurer |
Policy excess | You usually pay it | Usually refunded, or not paid at all |
No-claims bonus | Usually reduced | Usually kept once costs are recovered |
Premium at renewal | Likely to rise | May still rise slightly |
Replacement car | Only if your policy includes one | You can claim a similar car from the at-fault insurer |
Injury compensation | You cannot claim from anyone else | You can claim from the at-fault insurer |
Sometimes both drivers share the blame. This is called split liability. Insurers agree a split, such as 50/50 or 70/30.
Each insurer then pays its share of the other side’s losses. For example, if you are 70% to blame, your insurer pays 70% of the other driver’s costs, and you can recover 30% of yours. A split liability claim usually counts as a fault claim on your no-claims bonus.
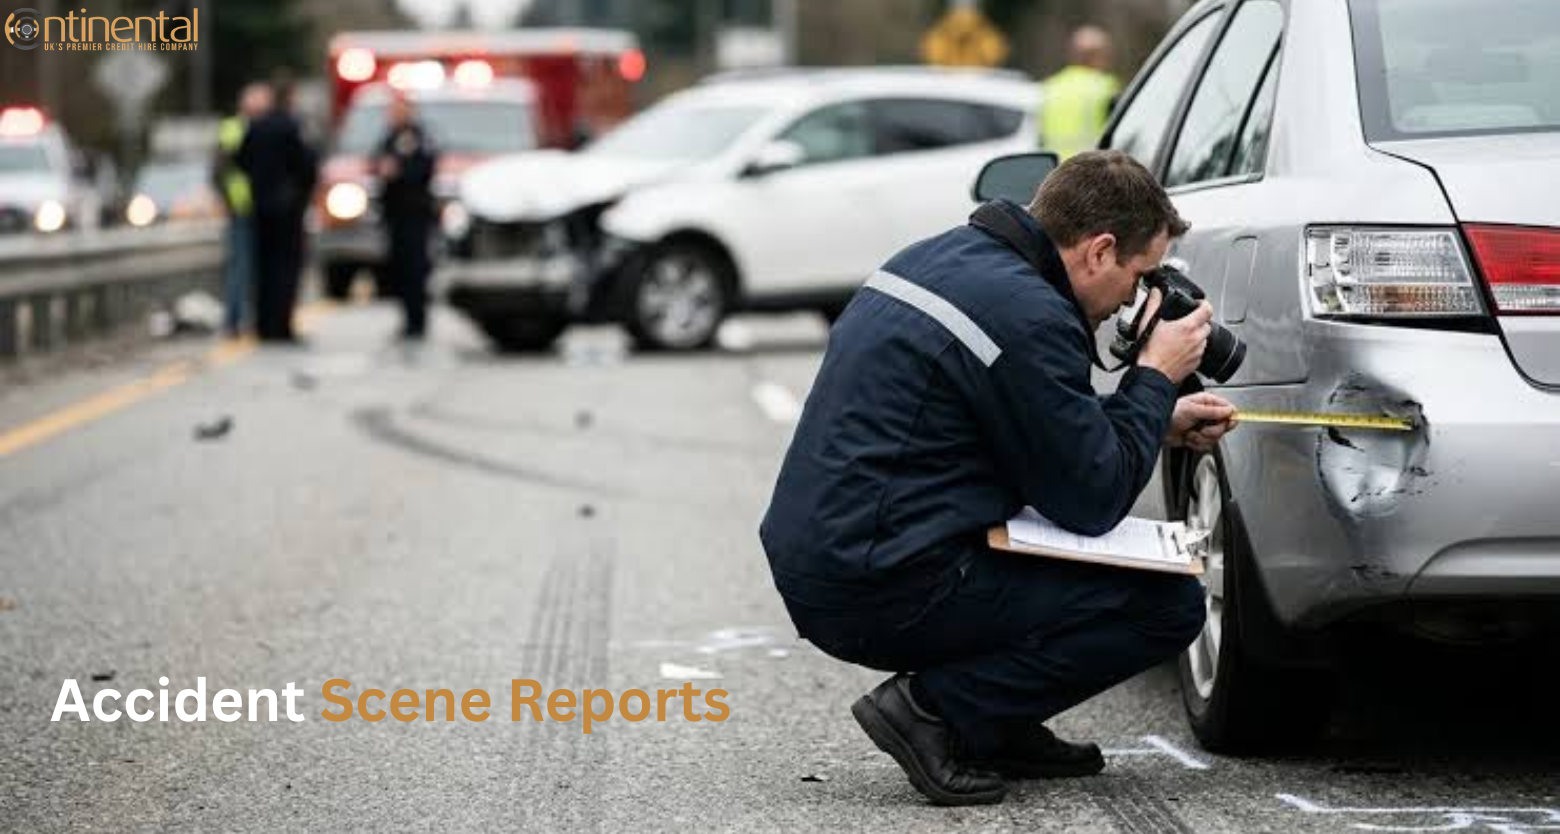
Insurers decide fault by looking at the evidence and comparing it with the rules in the Highway Code. The driver who broke a rule, or failed to take reasonable care, is usually found at fault.
Insurers look at:
Some situations follow common patterns:
When there are no witnesses and the stories do not match, insurers may agree a 50/50 split. That is why evidence matters so much.
Sometimes the at-fault driver’s insurance denies the claim. They may say their driver was not to blame, or that your evidence is not strong enough.
If this happens:
In the US, people talk about a car accident and suing the at-fault driver. In the UK, this means starting court action against the driver, with their insurer handling the defence. Most claims settle long before court. Generally, you have three years to start court action for an injury and six years for damage to your car.
Both drivers are affected, but in different ways. The driver at fault takes the bigger hit to their no-claims bonus and premium. The driver not at fault is mostly protected, but not always fully.
Your insurer cannot recover its costs from anyone else. So the claim counts against you.
If your insurer gets all its money back from the other driver’s insurer, your no-claims bonus should stay the same. Insurers call this “bonus allowed”.
There are a few catches:
Tip: You must tell your insurer about any accident, even if you do not want to claim. You can ask for it to be recorded as “notification only”. This should not reduce your no-claims bonus.
A car accident with no insurance on the other side can feel frightening. But if you were not at fault, you can still get paid.
The Motor Insurers’ Bureau (MIB) was set up in 1946 to pay victims of uninsured and untraced drivers. By law, every UK motor insurer must be a member and help fund it.
In a not at fault accident with no insurance on the other side, you have two main routes:
If the driver drove off and cannot be found, it is called a hit-and-run. The MIB handles these under a separate scheme for untraced drivers. Report the crash to the police straight away and note the other car’s registration if you can.
This is a car accident with no insurance on your side, but you were not at fault. You can usually still claim for your losses from the at-fault driver’s insurer. But you will still face penalties for driving without insurance, and the police may seize your car. Expect your claim to be checked closely, and get legal advice early.
The driver at fault, through their insurer, pays for the other driver’s repairs. Who pays for the at-fault driver’s own car depends on their cover.
Situation | Who pays for your repairs |
You were not at fault | The at-fault driver’s insurer |
You were at fault, with comprehensive cover | Your own insurer, minus your excess |
You were at fault, with third-party cover only | You pay |
Blame is split | Each side recovers its share from the other |
The other driver had no insurance | Your own insurer (comprehensive) or the MIB |
You were at fault and had no insurance | You pay for everything |
In an at fault accident with no insurance, you pay for your own car and may also face a bill for the other driver’s losses. This is on top of the fine and penalty points.
If you were not at fault, you do not have to use the garage the other insurer suggests. You can ask for your car to be fixed at a garage you trust. Keep every receipt and invoice.
In the US, people say a car is “totaled”. In the UK, we say it is “written off”. This happens when the insurer decides the car is too damaged, or too costly to repair compared to its value.
If your car is totaled and you were not at fault, the at-fault driver’s insurer should pay you its market value. That is what your car was worth just before the crash, not what you paid for it.
Written-off cars are put into one of four categories:
Category | What it means | Can it go back on the road? |
Cat A | Badly damaged. Must be crushed. | No |
Cat B | Body must be crushed. Some parts can be saved. | No |
Cat S | Damage to the frame or structure. Can be repaired. | Yes, once repaired and re-registered |
Cat N | No structural damage. Can be repaired. | Yes |
Cat S and Cat N replaced the old Cat C and Cat D in October 2017.
If you think the offer for your car is too low, you can challenge it. Find adverts for the same make, model, age, and mileage, and send them to the insurer as proof.
What if your car is totaled, you had no insurance, and you were not at fault? You can usually still claim the market value from the at-fault driver’s insurer. But you still face penalties for driving uninsured, and your claim will likely be checked closely.
If you were not at fault and you need a car, you can claim a replacement while yours is off the road. The cost is claimed back from the at-fault driver’s insurer.
UK law aims to put you back where you were before the crash. If you drove a family estate or a work van, a tiny hatchback may not meet your needs. That is why non-fault drivers can often get a like-for-like car, meaning a vehicle of a similar size and type.
There are two main types of replacement car:
Courtesy car | Like-for-like replacement (credit hire) | |
Who provides it | Your own insurer | A specialist hire or accident management company |
Type of car | Usually a small, basic car | A car similar to your own |
When you get it | Usually only while your car is repaired at an approved garage | While your car is repaired, or for a reasonable time if it is written off |
Who can get it | Depends on your policy | Drivers who were not at fault |
Who pays | Included in your policy | Recovered from the at-fault driver’s insurer |
You only get a replacement car if your own policy includes one. Many policies offer a small courtesy car, and some only while your car is in an approved garage. If your car is written off, you may get nothing at all. Check your policy documents.
A replacement car may still be possible. But you may only recover part of the cost, so get advice before you agree to anything.
If you were driving for work, in a company car or your own vehicle, the same rules apply. Tell your employer straight away. If your car or van is how you earn a living, such as a taxi or delivery van, the loss of it matters even more, and you may also be able to claim lost earnings.
Tips before you accept a replacement car:
The difference between at-fault and non-fault claims comes down to one thing: who pays. If you caused the crash, your own insurer pays, and your no-claims bonus and premium usually suffer. If you were not at fault, the other driver’s insurer should cover your repairs, a replacement car, and your other losses.
The best thing you can do is protect your claim from the start. Stay calm, gather evidence, never admit blame at the scene, and tell your insurer quickly. If the other driver has no insurance, or their insurer denies your claim, you still have options through the MIB, your own insurer, or a solicitor.
Key takeaways
It can, but usually only a little. Your no-claims bonus should stay the same once your insurer recovers its costs. But all claims are recorded, and some insurers may still charge slightly more at renewal.
If you claim through your own insurer, you may need to pay it at first. You should get it back once your insurer recovers its costs from the other side. If you claim directly against the at-fault insurer, you usually pay no excess.
In a not at fault accident with no insurance on the other driver’s side, you can still claim. Your own insurer can pay if you have comprehensive cover, or you can claim from the Motor Insurers’ Bureau (MIB). Many policies also protect your no-claims bonus in this situation.
Yes, in most cases you can still claim your losses from the at-fault driver’s insurer. But driving without insurance is still an offence. You may get a fine, penalty points, and have your car seized, so get legal advice early.
Call the police straight away and report it as a hit-and-run. Write down the registration number, the car’s make and colour, and anything else you remember. You may be able to claim through the MIB’s scheme for untraced drivers.
Yes. If blame is shared, you can still recover part of your losses. For example, if you were 30% to blame, you may recover 70% of your costs.
It is best not to. Saying sorry can be taken as admitting fault, even if you only meant to be polite. Check that everyone is okay, swap details, and let the insurers decide who is to blame.
If you were driving for work and another driver caused the crash, you can claim from their insurer, just like any other non-fault accident. Tell your employer straight away, as their insurer may need to know. If you were hurt at work in another way, such as a fall, you may be able to claim through your employer’s insurance instead.
Yes. In England and Wales, most lower-value road traffic injury claims go through the Official Injury Claim service. For crashes on or after 31 May 2025, whiplash lasting up to two years is worth £275 to £4,830 under a fixed legal tariff. You can also claim for lost earnings, treatment, and travel costs.
Tell your insurer about the accident as soon as possible. For a personal injury claim, you usually have three years from the date of the accident to settle or start court action. For damage to your car, the limit is usually six years. Do not wait, as evidence is easier to gather early.
A crash you did not cause should not leave you stuck at home, unable to get to work, school, or appointments. If your car is off the road after a non-fault accident, Continental Car Hire Ltd can keep you moving with a like-for-like replacement vehicle.
We are a professional car accident management company. We help drivers, families, and business users get back on the road quickly after an accident that was not their fault. While you focus on your recovery and your claim, we deal with the at-fault driver’s insurer for the cost of your hire.
Had an accident that wasn’t your fault? Contact Continental Car Hire Ltd on +442087437469 today to check if you qualify for a replacement vehicle.
A non-fault accident car hire UK service gives you a replacement car
A non-fault accident car hire UK service gives you a replacement car
A non-fault accident car hire UK service gives you a replacement car
A non-fault accident car hire UK service gives you a replacement car
A non-fault accident car hire UK service gives you a replacement car
A non-fault accident car hire UK service gives you a replacement car
Copyright © 2026 Continental Car Hire Ltd. All Rights Reserved.
Continental Car Hire Ltd is authorised and regulated by the Financial Conduct authority (FRN 711301)